Vision Insurance Explained: Why Covered Glasses Can Still Come With a Bill
You choose a pair of glasses, hand over your insurance information and wait for the final price. Then come the questions: Which lenses? Which coating? Are those frames within your allowance? Have you already used your eyewear benefit?
Suddenly, “glasses covered” feels less straightforward than it sounded.
Vision insurance can help with certain eye care expenses, but understanding its value takes more than checking the monthly premium. You need to know which services qualify, how much you still pay, and whether the places you want to use participate in your plan.
This guide explains those details in plain English. It focuses on coverage in the United States. All dollar amounts in the examples are hypothetical teaching figures, not actual quotes, market averages or promised savings.
What Is Vision Insurance?
Vision insurance is a benefit that helps pay for eligible vision care, such as routine eye examinations and prescription eyewear. Depending on the arrangement, it may be included in another benefits package or purchased separately.
Adult vision benefits are not automatically included in every health plan. HealthCare.gov states that Marketplace plans include vision coverage for children, while only some include it for adults. Its federal Marketplace does not sell separate vision plans.
For someone comparing coverage for the first time, three questions make a useful starting point:
- What eye care do I expect to use?
- What would that care cost with this plan?
- What would the same care cost without it?
The answers matter more than a general claim that a policy offers “great savings.”
Someone who regularly buys prescription eyewear has a different calculation from someone who expects only an examination. Even two people who both wear glasses may choose different plans because their lenses, preferred providers and replacement habits differ.
Routine Vision Care and Medical Eye Care Are Different Coverage Questions
An appointment to check your glasses prescription and an appointment to investigate an eye condition may involve different insurance benefits.
FAIR Health explains that health insurance commonly covers medically necessary eye care, while routine examinations and adult eyewear depend on the particular benefits offered. A separate vision plan can help fill some routine-care gaps.
Before a planned visit, describe why you are booking and ask the office which coverage it expects to bill. Provide both your medical insurance and vision benefit information when relevant.
Useful questions include:
- Is this appointment being scheduled as routine vision care or medical eye care?
- Is the prescription measurement included in the quoted price?
- Could any planned tests produce separate charges?
- Which benefits have you checked?
- What remains uncertain about my estimated payment?
An office may need information from the examination before it can determine every billing detail. The purpose of asking is to understand the process and likely costs, not to choose a billing category yourself.
How to Read a Vision Benefits Summary
A benefits summary is easier to understand when you read each line as a separate promise.
Look for the service, your payment, the plan’s contribution, the eligible provider and the date you can use the benefit. Avoid assuming that a generous amount on one line applies to everything else.
These are the main terms to identify.
Premium
The premium is the amount you pay to keep the coverage active.
If your share is $12 a month, your annual premium is:
$12 × 12 = $144
If coverage is deducted from your paycheck, use the actual number of deductions. A $6 deduction taken 26 times costs $156 annually. A $6 deduction taken 24 times costs $144.
That difference is small in this example, but the method matters. Compare annual amounts calculated on the same basis.
Copayment
A copayment, often shortened to copay, is a stated amount you pay for a covered service or item under the plan’s conditions.
Check whether the summary lists separate amounts for the examination and eyewear. Also ask whether additional services are included in those amounts.
For your comparison worksheet, place each expected copay on its own line. This helps prevent an examination copay from being mistaken for the entire appointment-and-glasses bill.
Allowance
An allowance is an amount available toward an eligible purchase under specified rules.
Suppose a hypothetical plan provides $150 toward eligible frames. If you select qualifying frames priced at $210, the starting difference is:
$210 − $150 = $60
That calculation assumes no additional discount or adjustment. It also says nothing about the lenses, which need their own calculation.
Ask for an itemized estimate showing exactly where the allowance is applied.
Benefit frequency
Frequency describes when you can use a benefit again.
Write down the next eligible date for each service instead of recording only “annual coverage.” Ask separately about examinations, frames, lenses and contacts.
MetLife, for example, tells members to check their particular benefit frequency and explains that its plans cover glasses or contacts once per applicable frequency. That is a reason to check your own schedule carefully rather than assume that every purchase has a fresh allowance.
Why an Eyewear Quote Needs Several Lines
When comparing glasses, ask the seller to separate the quote into components:
| Component | What to ask |
|---|---|
| Frames | Which amount does my benefit apply toward? |
| Prescription lenses | What is the price for my actual prescription and lens design? |
| Lens material | Is the quoted material included or an additional charge? |
| Coatings or treatments | Which have been included in the estimate? |
| Other services | Are fitting, delivery or other charges listed separately? |
| Final payment | What is my total after eligible benefits and adjustments? |
This is a shopping worksheet, not a statement that every plan uses these exact categories.
An itemized quote gives you something concrete to compare. “Glasses will be about $200” is much less useful than an estimate showing what you selected and how the benefit was calculated.
It also helps you make deliberate choices. If a feature increases your payment, ask the eye care professional what it does and whether there is another suitable option. You can then decide with both the price and purpose in front of you.
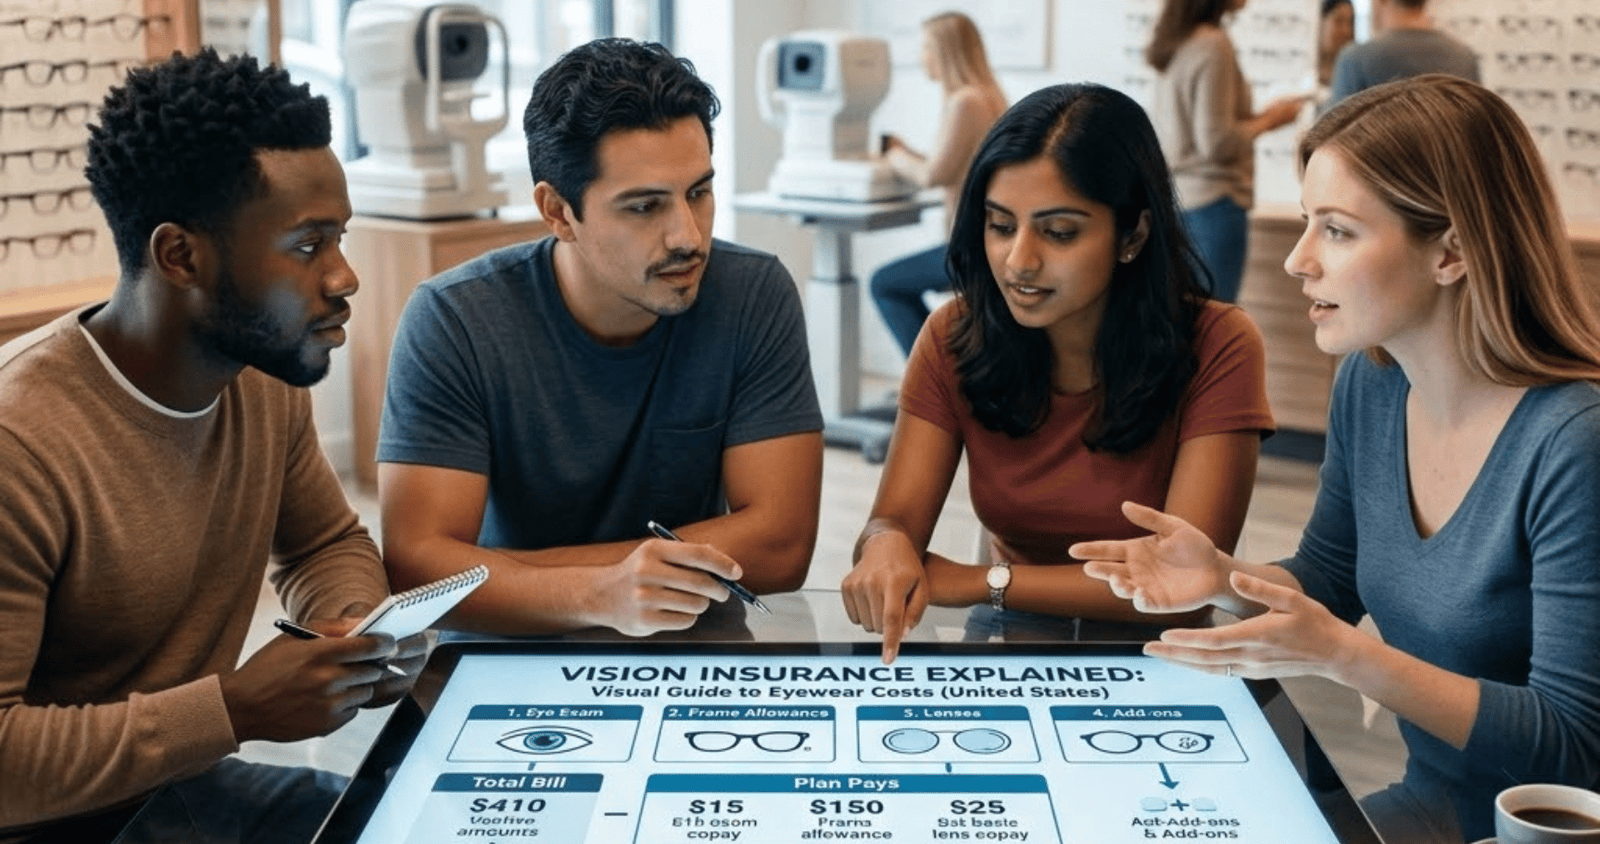
A Complete Example: From Monthly Premium to Final Cost
Imagine Elena is comparing a vision plan before buying new glasses.
For this fictional example, assume:
- Her annual premium is $144.
- Her covered examination copay is $15.
- Her covered basic-lens copay is $25.
- Her eligible frame allowance is $150.
- Her chosen frames cost $210.
- Her selected lens enhancements cost another $80 after applicable benefits.
- There are no other charges or discounts.
Her spending would be:
| Expense | Elena pays |
|---|---|
| Annual premiums | $144 |
| Examination copay | $15 |
| Basic-lens copay | $25 |
| Frames above the allowance | $60 |
| Lens enhancements | $80 |
| Total annual spending | $324 |
At the appointment and purchase, Elena pays $180. Across the whole year, including premiums, she spends $324.
Both numbers are useful. The first tells her what she needs available when purchasing. The second helps her judge the plan’s financial value.
Now suppose Elena obtains a cash quote of $410 for the same examination and eyewear specification.
Under these assumptions:
$410 − $324 = $86 in annual savings
If an equivalent cash package costs $295 instead, the result changes:
$324 − $295 = $29 more with the plan
These examples do not establish whether vision insurance is generally worthwhile. They demonstrate why the cash comparison needs to be part of the decision.
Compare the Same Glasses Before Comparing Prices
Two eyewear quotes can look similar while describing different products.
One may include the lens design you requested. Another may begin with a basic lens price and add your prescription requirements later. One may include adjustments or a particular remake arrangement, while another handles those separately.
For a fair comparison, give each seller the same requirements and ask them to identify any differences.
Record:
- The frame model or a clearly comparable alternative.
- The lens design and material.
- Any selected coatings or treatments.
- The final amount you would pay.
- The conditions for adjustments, returns or remakes.
- Any expenses still awaiting confirmation.
Avoid using the highest advertised retail price as your only measure of savings. The relevant alternative is a suitable purchase you would realistically make.
If you would never buy a $600 pair of glasses, saving against that price may say little about your household budget.
Contacts Need Their Own Calculation
If you wear contacts, build a contact-lens worksheet instead of reusing the glasses estimate.
Ask the plan and provider to price:
- The examination.
- Any contact-lens fitting or evaluation.
- Your prescribed lenses in the quantity you expect to purchase.
- Any remaining amount after the applicable benefit.
- Backup glasses, if you intend to buy them.
Do not enter a benefit for both glasses and contacts until your plan confirms that both are available in the same period.
Here is a fictional example.
Marcus pays $120 annually for a plan. His examination and fitting charges total $65 after benefits. His prescribed contact supply costs $360, and the applicable allowance is $150.
Assuming no other adjustments:
$120 + $65 + ($360 − $150) = $395
If Marcus also plans to spend $90 on backup glasses without additional benefits, his total becomes $485.
Including that second purchase makes the estimate fit his actual plans. Leaving it out would make coverage appear more affordable than his expected spending really is.
Check the Exact Provider Network
An insurer’s name alone may not identify the network attached to your benefits.
MetLife’s vision offerings, for example, use different named networks and describe different arrangements for participating and nonparticipating providers. Its guidance also explains that an out-of-network visit may require payment upfront and a reimbursement claim. Those details are product-specific.
Before enrolling, ask both the plan and office:
“Does this exact location participate in the network attached to this exact plan?”
Then check whether the answer covers the services you intend to purchase.
For your own records, save the plan name, network name, office location and date of confirmation. If eyewear will come from a different business, verify that purchase separately.
Convenience belongs in the comparison too. A lower estimated bill may be less appealing if using the plan requires a long trip or repeated time away from work. You do not need to assign those inconveniences a perfect dollar value, but you should acknowledge them.
Benefit Dates Can Change Your Budget
Consider two imaginary benefit schedules.
Plan A refreshes an eligible benefit each January. Plan B makes that benefit available 12 months after its previous use.
If you use the benefit in October, the next eligible date could be very different under those two schedules.
The lesson is not that one schedule always wins. It is that the word “yearly” is insufficient for planning a purchase.
Ask:
- When does coverage become effective?
- When can I first use each benefit?
- What exact date will each benefit become available again?
- Which purchase or service date controls eligibility?
- What happens if an order is placed before coverage ends but collected afterward?
Keep the answers beside your planned appointment dates. Do not count an allowance in your budget until you know it will be available for that purchase.
An Insurance Benefit and a Discount Program Work Differently
Some arrangements help pay for covered services. Others provide access to reduced prices.
FAIR Health distinguishes vision benefit packages from discount vision plans. The practical question is whether the arrangement contributes toward eligible care or gives you access to a negotiated discount.
For a fictional discount membership costing $60 annually, suppose your eligible purchases receive $45 in total discounts.
Your result is:
$45 saved − $60 membership fee = $15 additional spending
If your discounts total $140, your net saving is $80.
Either result depends on the purchases you actually make. Ask for final prices, membership charges and participating locations before treating a discount percentage as evidence of value.
What About Medicare?
Original Medicare does not cover routine eye examinations for glasses or contact lenses.
There is a specific eyewear exception: Part B covers one pair of glasses with standard frames or one set of contacts after each qualifying cataract surgery that implants an intraocular lens. Deductible, cost-sharing and supplier requirements apply. Some Medicare Advantage plans offer additional vision benefits.
If you have Medicare coverage, review the benefits you already hold before buying something additional.
Write down the precise need you are trying to cover: a routine examination, new glasses, contact lenses or care associated with an eye condition. Then ask which existing benefit, if any, applies to that need.
This avoids buying a plan based on a broad phrase such as “eye care” when your intended service requires a more specific answer.
How to Compare Two Plans Without Getting Lost
Start with one realistic year of expected purchases.
Use this structure:
Annual premiums + expected examination payments + expected eyewear payments + other planned charges = estimated annual spending
Then compare that total with an equivalent cash purchase.
Here is a fictional comparison:
| Annual expense | Plan A | Plan B |
|---|---|---|
| Premiums | $120 | $216 |
| Examination payment | $20 | $10 |
| Eyewear payment after benefits | $190 | $95 |
| Estimated total | $330 | $321 |
Plan B costs $96 more in premiums but $105 less for the listed care. It finishes $9 cheaper overall.
That small difference suggests the next questions should concern provider choice, convenience and the reliability of the estimates.
Now suppose the person decides not to purchase new eyewear that year. Under the same hypothetical examination charges, Plan A totals $140 and Plan B totals $226.
Expected use changes the result. Run the comparison around care you reasonably anticipate, and keep optional purchases separate.
A Family Worksheet Should Start With People
A family has one household budget, but its members may have different eye care needs.
Imagine a household where one adult expects an examination only, another intends to buy contacts, and a child may need new glasses.
Create a row for each person:
| Person | Planned care | Estimated payment after benefits | Details to confirm |
|---|---|---|---|
| Adult one | Examination | Obtain quote | Examination eligibility |
| Adult two | Examination and contacts | Obtain quote | Fitting and contact benefit |
| Child | Examination and glasses | Obtain quote | Existing coverage and eyewear terms |
Add the annual family premium once, after totaling the individual expenses.
Also check whether children already have relevant benefits under existing health coverage. Marketplace plans include pediatric vision benefits, but the specific plan documents explain how those benefits work.
The worksheet prevents you from assuming that everyone will use the same allowance or visit the same provider.
Questions to Resolve Before Paying for Coverage
Before enrolling, collect clear answers to these questions:
- What is my full annual premium?
- Is there a minimum enrollment commitment?
- When does coverage begin?
- Which exact network applies?
- What are my next eligible benefit dates?
- What would my intended examination and eyewear cost?
- Which quoted features receive benefits?
- Can I use benefits for both glasses and contacts?
- What happens if eyewear is lost or damaged?
- How are purchases outside the network handled?
- Are there claim deadlines?
- What are the renewal and cancellation terms?
Ask for the benefit document as well as the sales summary. If a detail could change your decision, seek written clarification.
A useful question is specific: “Will this $240 frame purchase qualify for this allowance at this location on this date?” That gives the representative something concrete to check.