Car Insurance Explained: What You Pay, What It Covers and Who Gets Paid
You reverse out of a parking space and hit another car. Your bumper is damaged, the other driver needs repairs, and someone complains of neck pain.
You have car insurance. But does that mean your insurer pays every bill?
The answer depends on which parts of the policy you bought. One part may cover the other driver’s repairs. Another may cover your own car. Medical expenses can fall under a different section.
This guide explains those differences using U.S. insurance terminology. Requirements and coverage vary by state and policy. All dollar examples are illustrations, not quotes or promised claim payments.
What is car insurance?
Car insurance is a contract: you pay an insurance company a premium, and it agrees to pay for certain covered losses under the policy’s terms.
Depending on your coverage, those losses may include damage you cause to someone else, damage to your own car, or accident-related injuries.
You do not build a personal repair fund with your premiums. You pay to have protection available during the insured period, even if you never make a claim. The declarations page summarizes your vehicles, dates, limits and selected coverage; the full policy explains the conditions and exclusions.
What does car insurance cover?
Start with the bill you are worried about.
| The bill or situation | Coverage to look for |
|---|---|
| You injure someone in an accident you cause | Bodily injury liability |
| You damage another person’s car, fence or other property | Property damage liability |
| Your car is damaged in a crash or rollover | Collision |
| Your car is stolen or damaged by events such as hail, fire or flood | Comprehensive |
| You or your passengers need treatment after an accident | Medical payments or personal injury protection, depending on the policy |
| An at-fault driver has no insurance or insufficient coverage | Uninsured or underinsured motorist coverage |
These coverages have different limits and conditions. Uninsured motorist protection for injuries and vehicle damage may be separate, and hit-and-run rules vary. Personal injury protection, often called PIP, may also cover certain lost earnings and other eligible expenses.
The question to ask is specific: “If this happens, which section of my policy would respond?”
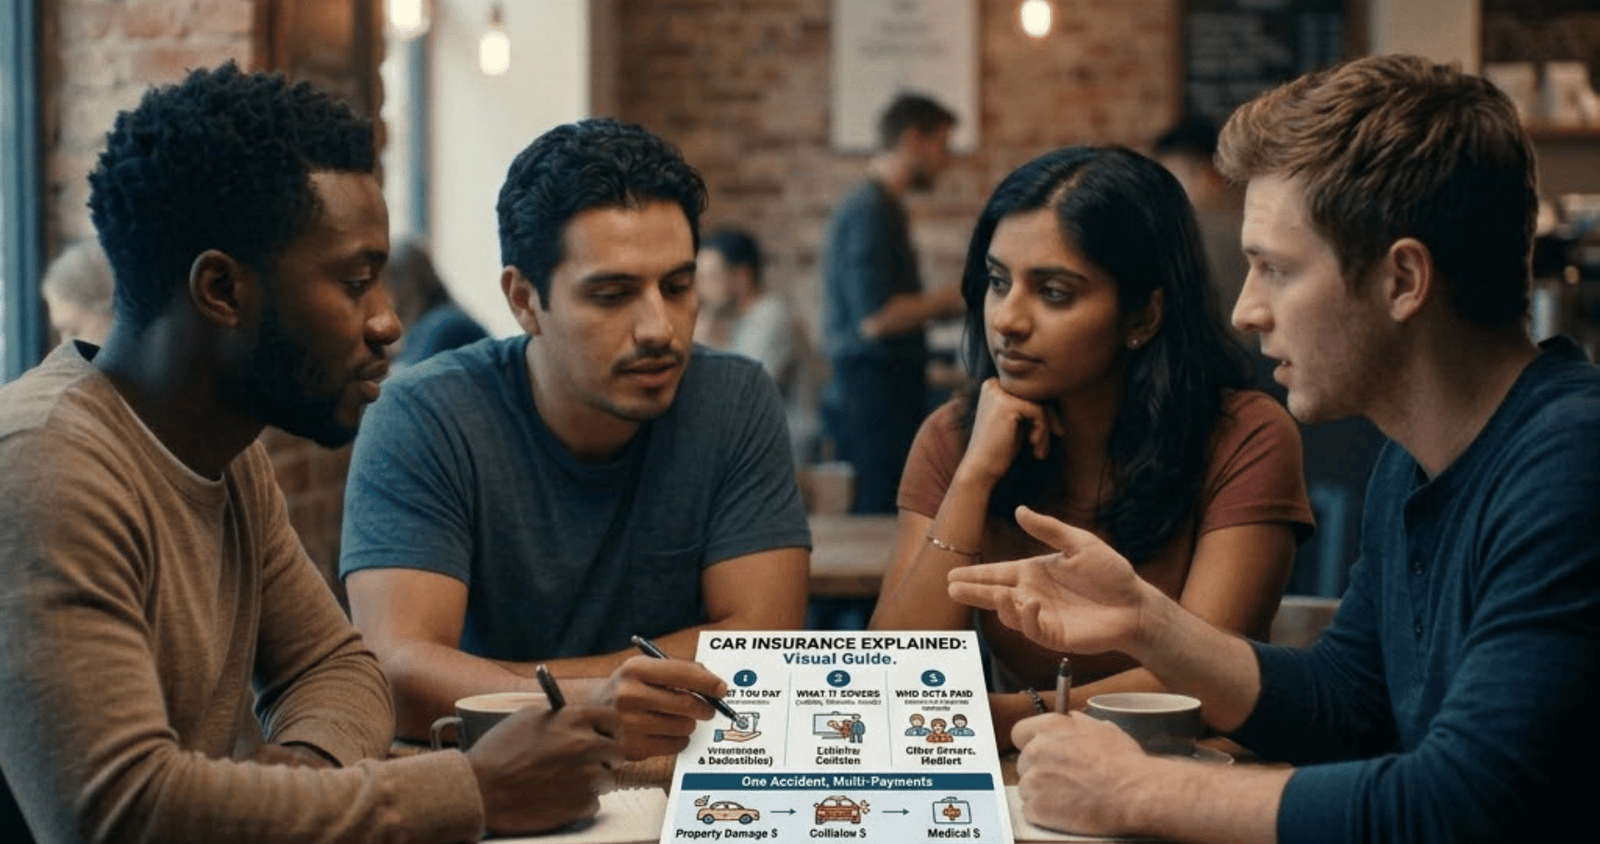
One accident, two different repair bills
Imagine you cause a crash with these repair costs:
The other driver’s car: $4,000
Your car: $3,000
Your collision deductible: $500
Assuming both repair amounts are accepted, applicable limits are sufficient and no exclusion applies:
| Payment | Illustrative result |
|---|---|
| Your property damage liability pays for the other car | $4,000 |
| Your collision coverage pays toward your car | $2,500 |
| Your share of your car’s repair bill | $500 |
Without collision coverage, your liability insurance would not pay your own $3,000 repair bill. This distinction follows the different purposes of liability and collision coverage.
Ask yourself: if you had to pay the entire repair bill tomorrow, where would that money come from?
Premium, deductible and limit: three different numbers
Your premium buys the insurance. Your deductible is the portion of a covered claim you bear when one applies. Your limit is the maximum payable under the relevant coverage.
For example, suppose a covered repair costs $2,400 and the applicable deductible is $1,000. With no other adjustments, the insurer’s share would be $1,400.
If the covered damage is only $700, that same deductible leaves no insurer payment.
A higher deductible can reduce the premium, but you need to be able to afford it after a loss.
What does 100/300/100 mean?
For a policy using split liability limits, it means:
$100,000 for bodily injury to one person.
$300,000 for bodily injury across one accident.
$100,000 for property damage in one accident.
These are separate ceilings, not one combined pot. This is an example, not a universal minimum or a personalized recommendation.
Does “full coverage” cover everything?
No. “Full coverage” is informal shorthand, often used for liability plus collision and comprehensive. It does not describe a universal policy that pays every possible expense.
Ask for the actual coverage list. Rental reimbursement and roadside assistance may require separate selections. Rental benefits can have daily and total limits.
For example, imagine your rental benefit allows $40 per day, but the car you choose costs $58 per day. That leaves an $18 daily difference before considering taxes, fees or other policy restrictions.
What usually is not covered?
A standard auto policy generally does not pay for routine maintenance, ordinary wear or a mechanical breakdown unrelated to a covered event. Loose belongings, such as a phone or laptop, are also generally outside the car’s physical damage coverage.
Paid delivery or rideshare work can create another gap. A personal policy may exclude that use, so ask your insurer about the exact work you do before relying on coverage.
“Does this cover my car?” is only half the question. Also ask, “Does it cover the way I use my car?”
What if the car is totaled but you still owe money?
A total-loss settlement generally reflects the car’s value before the loss, subject to the policy and applicable adjustments. It does not automatically match your loan balance.
Consider this simplified example, ignoring deductibles and other adjustments:
| Item | Amount |
|---|---|
| Outstanding car loan | $22,000 |
| Vehicle settlement | $18,000 |
| Remaining loan balance | $4,000 |
Gap coverage may help with an eligible difference between the vehicle’s value and the loan balance. Check its terms rather than assuming every outstanding charge qualifies.
How much does car insurance cost?
There is no single price that works for every reader. Your vehicle, location, driving history, mileage, selected coverage and insurer can affect the quote. State rules also affect which rating factors are permitted.
Compare matching coverage, limits and deductibles. A cheaper quote may simply leave you paying more after a loss.
For a practical comparison, imagine:
Policy A costs $110 monthly with a $500 collision deductible.
Policy B costs $95 monthly with a $1,000 collision deductible.
Policy B saves $180 a year but exposes you to another $500 on a collision claim. That is about 2.8 years of savings to match the additional deductible, assuming unchanged premiums. It does not predict whether a claim will happen.
What should you check before buying?
Use these questions when reviewing a quote:
What coverage does my state require?
What does my lender or lease require?
What are the liability limits?
What are the collision and comprehensive deductibles?
Which drivers and vehicle uses are covered?
Are rental reimbursement and roadside assistance included?
When does coverage begin?
Get unclear answers in writing. If you switch insurers, coordinate the dates so you do not leave a coverage gap.
What should you do after an accident?
Check for injuries and seek emergency help when needed. When safe, exchange driver and insurance details, photograph the scene and damage, and collect witness information.
Notify the insurer promptly. Keep your claim number, receipts and written communications. Before repairs, confirm what inspection or authorization the insurer needs. If a claim is denied, request the explanation and relevant policy wording in writing.