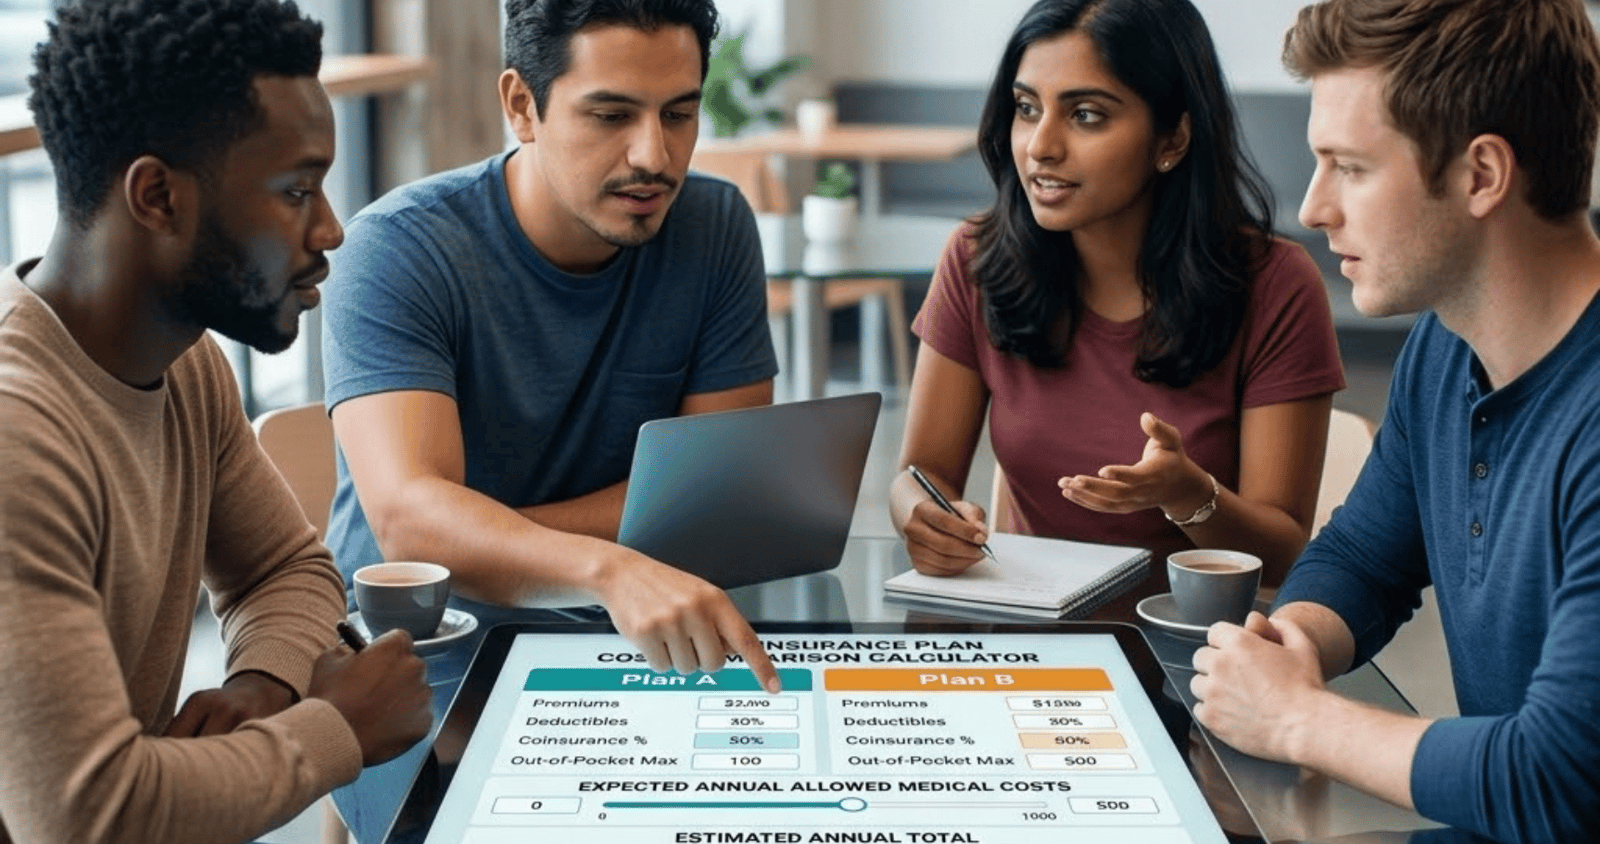
A lower monthly premium can look like an easy win. But what happens when you actually need care? Compare two health insurance plans using your own premiums, deductibles, coinsurance and expected medical costs. This calculator separates the price of keeping coverage from the amount you may pay when you use it, then brings both figures together in one annual comparison.
You can explore a quiet year, a year with more treatment, or a scenario where you reach a plan’s out-of-pocket maximum. The results show how the numbers change under the tool’s assumptions. They do not tell you which doctors are covered, which prescriptions are available, or whether a particular claim will be accepted.
This is a simplified calculator for one person with U.S.-style coverage over one complete plan year. It works best when the medical expenses being compared follow one deductible and one coinsurance percentage. It does not model family limits, visit copays, separate prescription deductibles, free preventive services or care outside the plan’s coverage.
Start with the yearly bill, not just the monthly price
Imagine comparing two plans on a checkout screen. One costs $300 a month and the other costs $420. Before you look at anything else, the first plan appears to save $120 every month.
That difference matters. Over twelve months, it becomes $1,440. However, the premium is only one part of the calculation. Once you add the medical expenses you may have to pay yourself, the difference can shrink, grow or reverse.
HealthCare.gov describes annual costs as a combination of premiums and the amounts you pay when you receive care. Its guidance encourages comparing total yearly costs rather than judging a plan only by its monthly price.
This tool gives you a place to make that comparison without guessing what a plan should cost. It does not generate market prices, collect quote requests or insert an insurer’s offer. You supply the plan figures and the medical spending scenario. The calculator performs the arithmetic and shows the result.
What you need before using the calculator
Have the figures for both plans beside you. A quote and the plan’s benefit summary are useful starting points. Look for your monthly premium, annual deductible, coinsurance percentage and individual in-network out-of-pocket maximum. If you cannot identify a figure confidently, ask the plan provider to confirm it before using the result to compare options.
Also prepare an estimate of the allowed medical costs for the care you want to model. An insurer’s cost estimator or a previous explanation of benefits may help. This input is different from your personal payment: it represents the covered amount before the calculator divides the expense between you and the plan.
You do not need to enter your name, diagnosis, address, insurance identification number or contact details. The calculator needs financial inputs only. Avoid putting private medical information into an amount field or any surrounding website form.
The five inputs for each plan
1. Your monthly premium
Enter the amount you expect to pay each month for your own coverage. For this comparison, use the payment remaining after an employer contribution or subsidy already reflected in your quote. Do not subtract the same contribution a second time.
The tool multiplies this figure by twelve. A monthly payment of $300 becomes $3,600 for a complete year. A monthly payment of $420 becomes $5,040. These amounts are included even when you enter zero medical spending, because the model assumes coverage stays active for all twelve months.
If your premium changes during the year, this version will not automatically account for the change. Its annual total assumes one constant monthly amount. Keep that limitation in mind when comparing a full-year estimate with a situation involving only a few months of coverage.
2. Your annual deductible
For the care modeled here, the deductible is the amount you pay before the plan begins sharing the remaining expense through coinsurance. If you enter $2,000, the tool assigns you the first $2,000 of eligible medical costs, provided that much care occurs.
You do not automatically spend the full deductible. If the allowed cost you enter is only $600, the modeled medical share is $600. The tool does not add another $2,000 on top of it. That distinction is useful when exploring a year with relatively little care.
This calculator begins at the start of a plan year, with nothing already paid toward the deductible. It is not a remaining-year estimator. Entering a partially used deductible alongside a full year of premiums would mix different time periods and could produce a misleading comparison.
3. Your coinsurance percentage
Coinsurance is your percentage of a covered expense after the applicable deductible. Enter your share, not the insurer’s share. If the plan pays 80% and you pay 20%, the input should be 20. HealthCare.gov explains this percentage using the plan’s allowed amount for a service.
The calculator accepts percentages from zero through one hundred. A zero means the modeled plan pays the remaining covered expense after the deductible, within the assumptions of this tool. A hundred means you bear the remaining expense until the entered out-of-pocket cap limits your share.
Many real plans have several cost-sharing arrangements. This version uses one percentage across all entered care. If one service uses a copay and another uses a different coinsurance rate, do not treat this simplified output as an exact reconstruction of those benefits.
4. Your annual out-of-pocket maximum
Enter the individual in-network maximum that applies to the care being modeled. This amount caps your medical share in the calculation. It does not cap the premium, which the tool adds separately.
HealthCare.gov explains that an out-of-pocket limit generally applies to eligible in-network cost sharing. Premiums, uncovered services, out-of-network care and certain charges beyond allowed amounts are outside that limit.
For this model, the maximum must be at least as large as the deductible. If you enter a smaller number, the calculator asks you to correct it. Check that you have not mixed an individual deductible with a family maximum, or taken the two figures from different coverage tiers.
5. Expected annual allowed medical costs
Enter the covered, in-network allowed cost before your own share is calculated. Do not enter just the amount you expect to pay after insurance. Doing that would apply the cost-sharing calculation to an amount that has already been reduced.
There is a separate medical-cost field for each plan. This lets you compare the same anticipated care when the plans recognize different negotiated prices. If you do not know whether the prices differ, using an equal amount creates a controlled illustration of the benefit differences. It does not establish the actual price under either plan.
For a useful comparison, keep the expected care consistent. Comparing a year with one appointment under Plan A against a year with major treatment under Plan B would tell you little about the plans themselves. Change the care scenario deliberately and describe the assumption to yourself before interpreting the result.
How your result is calculated
The calculator follows four steps:
Multiply your monthly premium by twelve.
Assign the allowed medical expense to your deductible until that deductible is reached.
Apply your coinsurance percentage to the remaining allowed expense.
Cap your combined deductible and coinsurance payment at the entered out-of-pocket maximum, then add annual premiums.
Here is the same process in mathematical form:
Annual premiums = monthly premium × 12

Deductible paid = smaller of allowed medical costs and deductible

Uncapped coinsurance = larger of (allowed costs − deductible) and 0
                      × your coinsurance percentage

Medical share = smaller of:
                deductible paid + uncapped coinsurance
                OR out-of-pocket maximum

Estimated annual total = annual premiums + medical share
This formula is the model implemented in the code below. It is not a promise about how every health plan processes every service. It assumes that all entered expenses follow the same deductible and coinsurance arrangement and count toward the same maximum.
A complete comparison using example figures
The following figures are invented to demonstrate the calculator. They are not insurer quotes, average premiums or suggested coverage levels.
| Input | Plan A | Plan B |
|---|---|---|
| Monthly premium | $300 | $420 |
| Annual deductible | $2,000 | $500 |
| Your coinsurance | 20% | 10% |
| Out-of-pocket maximum | $6,000 | $3,500 |
| Allowed medical costs | $10,000 | $10,000 |
For Plan A, annual premiums are $3,600. You pay $2,000 toward the deductible. The remaining $8,000 generates $1,600 in coinsurance, giving a medical share of $3,600. Adding premiums produces an estimated annual total of $7,200.
For Plan B, annual premiums are $5,040. You pay $500 toward the deductible. The remaining $9,500 generates $950 in coinsurance, giving a medical share of $1,450. Adding premiums produces an estimated annual total of $6,490.
In this particular scenario, Plan B costs $710 less over the year, even though its monthly premium is higher. That result does not establish that Plan B is better in every situation. It shows what happens when these specific inputs are used in this specific model.
Explore more than one spending scenario
You do not have to predict your medical spending perfectly to learn something from the comparison. Try several clearly labeled possibilities and watch how the result changes. Keep the plan terms fixed while changing the allowed costs for both plans.
Using the example plans above gives these results:
| Allowed costs under each plan | Plan A annual total | Plan B annual total | Lower modeled cost |
|---|---|---|---|
| $0 | $3,600 | $5,040 | Plan A by $1,440 |
| $1,000 | $4,600 | $5,590 | Plan A by $990 |
| $10,000 | $7,200 | $6,490 | Plan B by $710 |
| $50,000 | $9,600 | $8,540 | Plan B by $1,060 |
These scenarios are arithmetic examples, not predictions about how much care a person will need. The $50,000 scenario reaches both entered medical caps. The zero-cost scenario includes premiums only.
Notice that the cost difference does not increase in a straight line. Deductibles, coinsurance and caps change which part of the calculation applies. That is why a single monthly premium comparison can miss an important part of the picture.
Understand each row in the results
Annual premiums show the cost of maintaining coverage for twelve months under the entered premium. This row stays the same when you adjust only medical spending.
Medical costs toward deductible show how much of your entered medical expense is allocated to the deductible. This amount can be lower than the full deductible when the spending scenario is small.
Coinsurance after applying the cap shows the additional medical amount assigned to you after the deductible, with the maximum already respected. The calculator does not keep charging coinsurance beyond that cap.
Your total modeled medical share combines the deductible and coinsurance rows. Do not add those two rows to this subtotal again; that would count the same expense twice.
Estimated annual total combines premiums and the modeled medical share. This is the number used to identify the lower-cost plan in the entered scenario.
Annual premiums plus the in-network out-of-pocket limit shows the premium-plus-cap figure. It is not another expense to add to the annual total. It is a separate reference showing the amount reached if your eligible medical share hits that maximum.
Avoid these common input mistakes
The first mistake is entering the insurer’s percentage instead of your own. Typing 80 where you should type 20 can radically change the estimate. Read the wording next to the percentage before copying it.
The second is mixing monthly and yearly amounts. Premiums are monthly in this tool; deductibles and maximums are annual. A $3,600 yearly premium entered as a monthly premium would become $43,200 after the calculator multiplies it by twelve.
The third is entering your expected personal bills as the allowed medical cost. The tool calculates your share from the allowed amount, so an already reduced number does not represent the intended input.
The fourth is comparing unlike scenarios. Use the same anticipated services under both plans, while allowing for different recognized prices if you have reliable estimates. If one set of costs excludes prescriptions and the other includes them, the totals do not answer the same question.
Finally, do not treat empty fields as zero. If you genuinely expect no modeled medical spending, enter zero in that field. Missing plan terms should be confirmed rather than replaced with a convenient number.
What the calculator deliberately leaves out
This version does not estimate copays, services covered before the deductible, separate drug deductibles, tiered coinsurance, embedded family rules or out-of-network benefits. It also does not calculate subsidies, tax effects or the value of a health savings account contribution.
Those limits are part of the model, not statements that your plan lacks those features. A plan with frequent fixed-price visits may produce a different real-world total from the simplified deductible-and-coinsurance scenario shown here.
The tool also does not evaluate access to care. A lower estimated total cannot tell you whether your preferred specialist participates, whether a medicine is covered, or whether a procedure requires approval. Review those questions separately before making a choice.
If your plan design does not match the assumptions, use the result only as a teaching example. A plan-specific estimator that applies the actual benefit rules is more suitable for estimating your own costs.