Start with the limit on your existing policy
You might know your monthly insurance premium without knowing your liability limit. That limit becomes important when someone claims you caused an injury or damaged their property.
Suppose a covered liability claim is larger than the amount your existing insurer can pay. The remaining financial responsibility does not disappear because your policy has reached its limit.
Umbrella insurance can provide additional protection for eligible claims. Understanding it requires looking at how your policies work together, rather than treating the umbrella as a separate promise to cover everything.
This guide explains common U.S. personal umbrella insurance arrangements. Actual coverage depends on policy wording and applicable law. All dollar examples are invented to explain the calculations, not claim forecasts, quotes or guaranteed payments.
What is umbrella insurance?
Personal umbrella insurance provides additional liability protection beyond underlying policies, such as auto, homeowners or renters insurance. Depending on the contract, it may also cover certain liability situations that an underlying policy does not cover.
It can address eligible liability payments and legal defense expenses under its terms. It does not generally pay to repair your own damaged car or home.
The word liability is central. The policy concerns financial responsibility to others, rather than providing an extra repair fund for your belongings.
Before buying, ask the insurer to identify the policies beneath the umbrella and explain how a covered claim would move between them.
How does it work with your existing insurance?
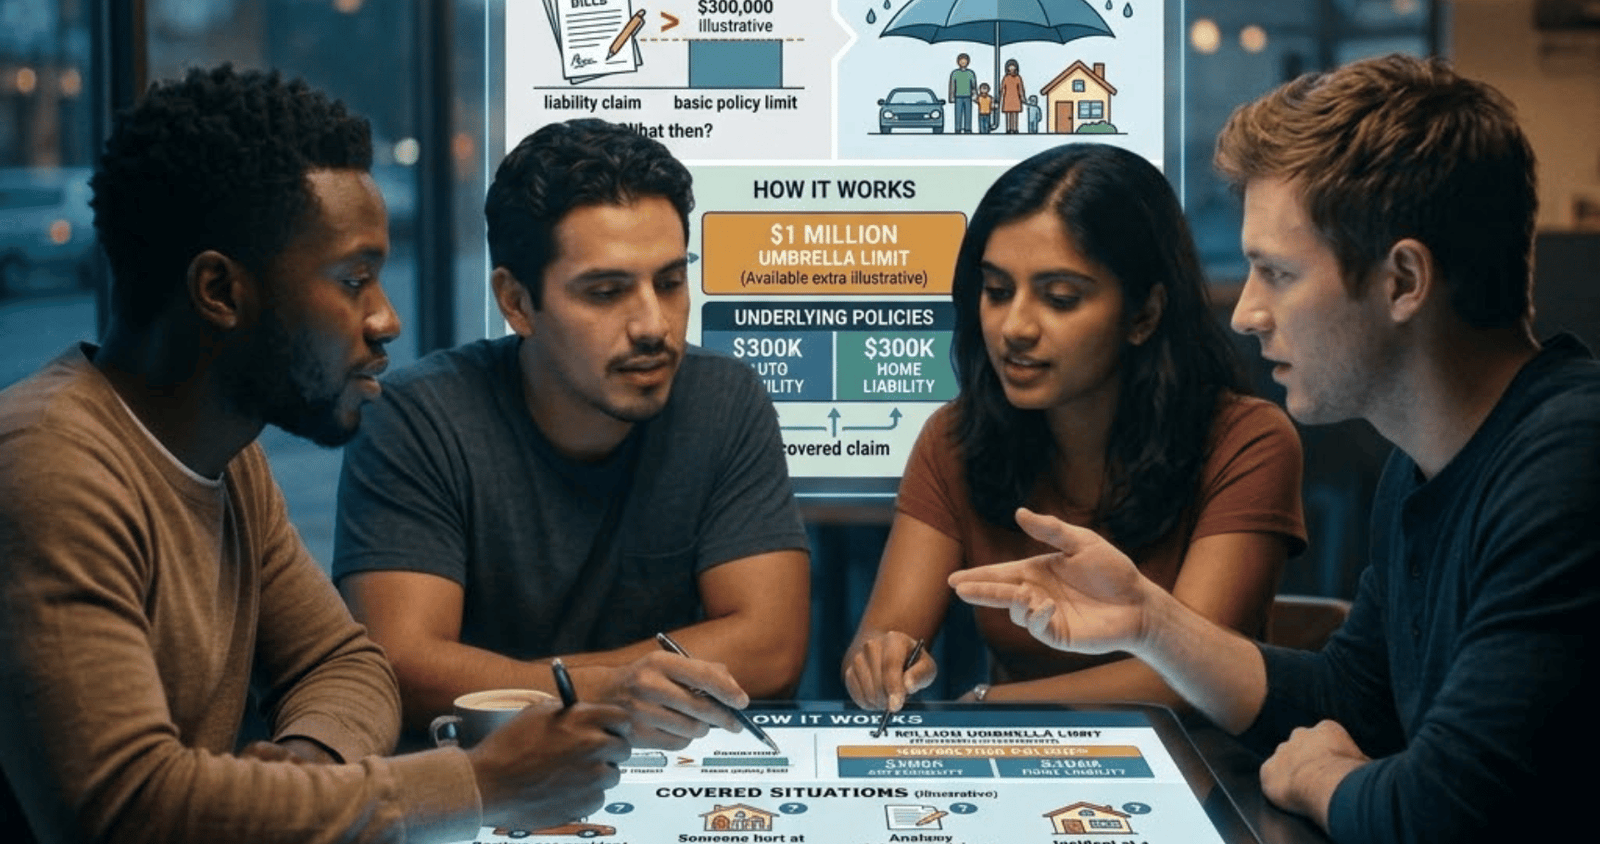
The policies beneath an umbrella are often called underlying policies. They provide the first layer of protection for the liability exposures they cover.
For an eligible claim that exceeds the relevant underlying limit, the umbrella may provide the next layer, subject to its own limit and conditions.
Think of the review as three separate questions:
- Does the underlying policy cover the incident?
- When does the umbrella become responsible under its terms?
- Does the umbrella also cover the claim?
A high umbrella limit cannot answer those questions by itself. You need to understand both contracts and how they connect.
A straightforward payment example
Imagine a covered liability settlement of $850,000 arising from an incident.
Assume:
- The relevant underlying policy pays its full $300,000 limit.
- The umbrella provides $1 million of available coverage above that layer.
- The claim satisfies both policies’ terms.
- There are no other adjustments.
- Legal defense expenses are excluded from this example.
The illustrative payment is:
| Payment layer | Amount |
|---|---|
| Total covered settlement | $850,000 |
| Underlying insurer’s payment | $300,000 |
| Remaining covered amount | $550,000 |
| Umbrella insurer’s payment | $550,000 |
The umbrella does not pay its entire $1 million limit simply because a claim occurred. It pays the eligible amount assigned to it, up to its available limit.
The $550,000 is also not an extra payment to the policyholder on top of the settlement. In this example, it helps fund the remaining covered liability.
What if the claim exceeds both layers?
Now change the covered settlement to $1.6 million, keeping the same limits.
| Payment layer | Amount |
|---|---|
| Total covered settlement | $1,600,000 |
| Underlying insurer’s payment | $300,000 |
| Umbrella insurer’s maximum available payment | $1,000,000 |
| Amount beyond both limits | $300,000 |
Under these simplified assumptions, the combined insurance layers provide $1.3 million. The remaining $300,000 sits beyond them.
This example illustrates why umbrella insurance is additional protection rather than unlimited protection. It also shows why you should distinguish the umbrella’s limit from the total potentially available across applicable layers.
Ask how the actual policy treats multiple claims, separate incidents and any aggregate limit. Do not assume one calculation applies unchanged to every situation.
What can umbrella insurance cover?
Depending on the policy, covered liability may involve bodily injury, damage to another person’s property or specified personal-injury offenses, such as libel or slander.
Some products can also address eligible liability involving rental properties or other disclosed exposures. These features are subject to the insurer’s terms and underwriting.
| Situation to discuss | Question for the insurer |
|---|---|
| A serious accident involving your car | Which underlying limit applies, and when does the umbrella respond? |
| Someone alleges injury at your residence | Does the incident qualify under both policies? |
| Damage involving another person’s property | Which exclusions or conditions could affect payment? |
| A claim involving an online statement | Are the alleged personal-injury offenses covered? |
| An incident at a rental property you own | Is that property and its use included? |
These are examples of questions, not promises that every listed situation will be covered.
What does umbrella insurance generally leave out?
Personal umbrella coverage typically does not reimburse your own injuries, replace your belongings or cover ordinary business losses. Intentional or criminal conduct and liabilities assumed under contracts can also fall outside coverage, depending on the wording.
Consider two different problems:
- Your own car needs repairs after an accident.
- Another person seeks damages from you because of that accident.
The first concerns damage to your vehicle. The second concerns liability to someone else. An umbrella should not be assumed to address both.
Likewise, “I was sued” does not automatically mean “the umbrella must pay.” The nature of the claim, the insured person and the applicable exclusions still matter.
Existing liability limits may need to increase
An umbrella insurer may require you to maintain specified liability limits on the policies beneath it. Requirements vary by company and exposure. GEICO, for example, publishes minimum underlying auto and property-liability requirements for its umbrella offering. Those figures are not universal industry requirements.
Before comparing umbrella premiums, ask whether your existing policies meet the proposed requirements.
Make a simple record:
| Underlying coverage | Current limit | Required limit | Change needed? |
|---|---|---|---|
| Auto bodily injury | Copy from policy | Confirm with umbrella insurer | Record answer |
| Auto property damage | Copy from policy | Confirm with umbrella insurer | Record answer |
| Home or renters liability | Copy from policy | Confirm with umbrella insurer | Record answer |
| Other relevant policies | List separately | Confirm individually | Record answer |
If a required change is needed, include its cost in your budget. The umbrella premium alone may not represent the full price of arranging the coverage.
Understand where the umbrella is supposed to begin
Do not assume an umbrella will automatically fill a gap caused by insufficient underlying insurance.
Describe your actual limits to the umbrella insurer and ask what happens if those limits fall below its requirements. Request the answer using the contract’s wording.
Here is a question you can use:
If my underlying policy pays less than the amount this umbrella expects beneath it, who is responsible for that difference?
Also ask what happens if an underlying policy is canceled, replaced or changed. Keep the response with your records.
This is especially useful when different companies provide your policies. Each insurer needs accurate information about the arrangement; sharing a broker or paying the bills together does not itself confirm that the limits match.
Does it cover the whole household?
A personal umbrella may extend protection to certain household members, but the definition of an insured person matters. Do not assume every person at the same address is included.
Give the insurer an accurate picture of your household and ask about any situation that is unclear.
Useful questions include:
- How are children living away at school treated?
- What if a household member has separate auto insurance?
- Are all regular drivers included in the information supplied?
- Does a change in household membership need to be reported?
- How is a jointly owned property treated?
The purpose is to identify who the contract protects before an incident makes the answer urgent.
What about freelance work or a small business?
Do not assume a personal umbrella covers liabilities arising from paid work. Personal umbrella policies generally exclude business-related losses, although the precise exclusions and any exceptions depend on the product.
Describe your work clearly when discussing coverage. “I work from home” could mean occasional remote employment, regular client visits, selling products or operating a service business.
Those are different activities. Ask which require separate business insurance or an endorsement.
If you receive income from renting property, distinguish that activity from other business work and have the insurer address it specifically. Avoid trying to fit every activity under a broad label such as “personal use.”
How are legal defense costs handled?
Umbrella insurance may provide legal defense protection for covered claims, but the contract determines when and how that protection applies.
Ask these questions before buying:
- Who selects and appoints the lawyer?
- When does the umbrella insurer become involved?
- Are defense expenses inside or outside the stated liability limit?
- What must I do if I receive a demand or lawsuit?
- Is consent required before agreeing to a settlement?
Do not assume that hiring a lawyer independently guarantees reimbursement. Ask the insurer how to follow the policy’s process.
Keep the answers practical. You want to know whom to contact and what documents to send, not merely whether the brochure mentions legal fees.
How much umbrella coverage should you consider?
Review your finances and your existing liability limits as a starting point. Progressive recommends assessing assets and discussing an appropriate limit with an insurer or adviser.
However, an asset total is not a prediction of a possible claim. Nor does a simple online calculation establish which assets could be reached under the law in your situation.
Prepare a discussion sheet with:
- Your current liability limits.
- Savings and investments you want to account for.
- Property ownership and other relevant financial interests.
- Household drivers and vehicles.
- Properties or activities that need specific review.
- The amount of uncovered expense you could realistically absorb.
Then request quotes at several available limits. Ask what changes between them besides price.
Use scenarios to understand the difference between limits
Suppose an illustrative arrangement has $300,000 of applicable underlying coverage.
Compare umbrella limits of $1 million and $2 million:
| Covered settlement | Payment needed above $300,000 | Beyond a $1 million umbrella | Beyond a $2 million umbrella |
|---|---|---|---|
| $700,000 | $400,000 | $0 | $0 |
| $1,500,000 | $1,200,000 | $200,000 | $0 |
| $2,500,000 | $2,200,000 | $1,200,000 | $200,000 |
This table assumes every claim qualifies, all relevant limits are available and the underlying insurer pays $300,000. It excludes legal expenses and other adjustments.
The examples show the arithmetic, not how likely those settlements are. They are useful for asking what a larger limit changes without implying that any limit eliminates every possible loss.
What does umbrella insurance cost?
Premiums vary with the insurer, selected limit and factors such as location, properties, vehicles and relevant claims or driving history. A current quote for your circumstances is more useful than a general advertised price.
Consider this invented annual budget:
| Change | Additional annual cost |
|---|---|
| Umbrella policy | $320 |
| Increased auto liability limits | $120 |
| Increased property-liability limit | $40 |
| Total additional cost | $480 |
The umbrella costs $320, but the example arrangement costs $480 more overall.
When comparing offers, ask whether each quote assumes the same underlying limits. Otherwise, a lower umbrella premium might be paired with more expensive required changes elsewhere.
Also compare the coverage itself. A price difference becomes meaningful when you can identify the change in protection or conditions.
How to compare two offers without getting lost
Keep one comparison sheet and use the same questions for each insurer.
| Detail | What to record |
|---|---|
| Insurer and policy | Exact product being quoted |
| Umbrella limit | Available amount and relevant restrictions |
| Underlying requirements | Required limits for each exposure |
| Insured people | Household members included |
| Insured exposures | Vehicles, properties and other activities |
| Broader coverage | Any protection beyond the underlying policies |
| Exclusions | Restrictions relevant to your circumstances |
| Defense arrangements | How legal expenses and representation work |
| Full annual cost | Umbrella plus required policy changes |
Leave uncertain answers blank until they are confirmed. An unanswered question is not evidence that something is covered.
Ask the representative to explain one realistic claim using your actual policy details. That conversation often reveals more than comparing a list of general benefits.
What to do if an incident could lead to a large claim
Find the reporting instructions in both the underlying and umbrella policies. Ask the relevant insurers when each must be notified, rather than assuming you should wait until the first insurer reaches its limit.
Preserve the information you have: photographs, correspondence, incident details and the contact information of people involved. Keep factual observations separate from guesses about fault or the final cost.
If you receive a demand letter or legal papers, record when they arrived and promptly pass them to the appropriate insurer or legal representative. Ask what response deadlines apply.
Keep a running record containing the claim references, people contacted, documents submitted and next steps. This helps you coordinate the process without repeatedly searching through messages.
Before accepting a settlement or incurring expenses you expect the insurer to pay, ask how the contract handles approval.