A rented home still contains a life you would have to rebuild
Think about what you would pack if you had to move tomorrow. The obvious things come first: a bed, a sofa, a computer and a television. Then come the less memorable items: work clothes, shoes, kitchen equipment, towels, chargers, bedding and everything tucked into cupboards.
Now imagine replacing those belongings in the same week. You would not be shopping gradually over several years. You would be trying to restore an ordinary routine while dealing with an unexpected loss.
Renters insurance addresses several financial problems that can arise when you rent your home. Understanding it starts with separating the building from your belongings, and separating damage to your property from your responsibility to other people.
This guide uses U.S. insurance terminology. Coverage depends on the policy and applicable state rules. Every dollar example below is illustrative; none is a quote, market average or promised claim payment.
What is renters insurance?
Renters insurance, also called tenants insurance, is coverage for people who rent their living space. Typical policies combine personal property protection with liability coverage and benefits for certain extra living expenses after an insured loss.
The landlord’s building insurance generally does not insure your possessions as your own contents policy would. Having an insured building therefore does not mean your clothing, furniture or electronics are insured.
Before comparing prices, write down three questions: What would I need to replace? What claims could be made against me? Where would I stay if a covered event made the rental unusable? Those questions give the policy’s different sections a practical purpose.
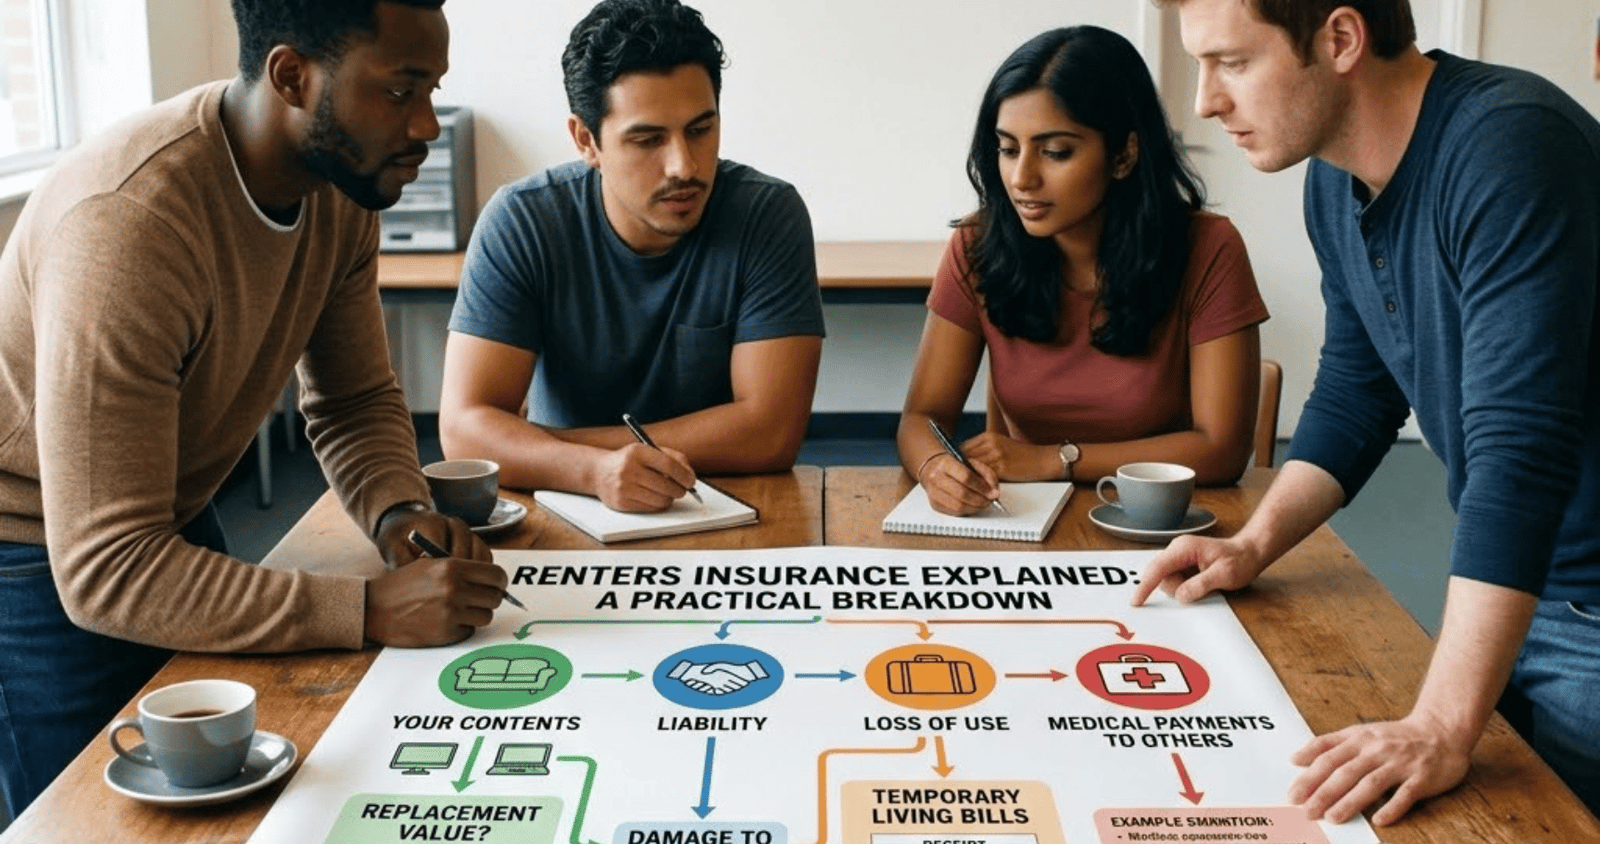
What are the main parts of a renters policy?
| Coverage | What it generally addresses | Question to ask |
|---|---|---|
| Personal property | Your belongings damaged or lost through an insured cause | Which events and belongings qualify? |
| Personal liability | Covered claims that you are legally responsible for injury or property damage to others | What exclusions and limits apply? |
| Loss of use | Eligible extra living expenses after a covered loss prevents you from living at home | What costs, amounts and time periods qualify? |
| Medical payments to others | Certain eligible medical expenses for others under the policy | Who qualifies and what is the limit? |
These are distinct benefits. A large contents limit does not tell you the liability limit or the amount available for temporary living expenses. New York’s insurance regulator identifies these four common coverage categories in its renters guidance.
Start by counting what you actually own
Do a room-by-room inventory before choosing a contents limit. California’s insurance regulator recommends recording possessions before a loss, when you can inspect them rather than trying to remember everything afterward.
Make the first pass simple. Open a blank note and list the rooms or areas you use. Walk through each area and record the objects you would need to replace. You can add prices and supporting records afterward. Trying to make the list perfect immediately is an easy way to postpone it indefinitely.
An example inventory
The figures below are invented to show how a household total can develop. Use your own possessions and current comparable prices instead.
| Area | Example belongings | Illustrative replacement budget |
|---|---|---|
| Bedroom | Bed, mattress, dresser and bedding | $2,200 |
| Living room | Sofa, table, television and lamps | $2,600 |
| Clothing | Everyday clothes, workwear, shoes and coats | $2,300 |
| Kitchen | Small appliances, cookware, dishes and utensils | $1,100 |
| Personal electronics | Laptop, tablet and accessories | $1,800 |
| Other belongings | Towels, books, sports equipment and miscellaneous items | $1,500 |
| Total | $11,500 |
The point is not that every renter needs $11,500 of coverage. It is that an estimate becomes more meaningful when you can see what sits behind it. One person might own very little furniture but expensive equipment. Another might have modest electronics and a large wardrobe.
Do not include the landlord’s refrigerator as your possession simply because you use it. Likewise, distinguish your belongings from a roommate’s belongings. For a jointly purchased item, note the ownership arrangement and ask how the proposed policy would treat it.
Replacement cost and actual cash value can produce different results
Actual cash value generally accounts for depreciation, reflecting age and use. Replacement cost coverage is intended to address the cost of a comparable replacement without that depreciation deduction, subject to policy limits and conditions. An applicable deductible can still reduce the payment.
Consider a simplified covered loss involving one computer:
| Item in the example | Amount |
|---|---|
| Cost of a comparable new computer | $1,200 |
| Assumed depreciated value | $650 |
| Applicable deductible | $250 |
If the accepted settlement basis is $650, subtracting the $250 deductible leaves $400. If the policy ultimately allows $1,200 under replacement-cost terms, subtracting the same deductible leaves $950. The $550 difference comes from valuation, not from changing the damaged item.
This example assumes adequate limits, no special restriction and satisfaction of all settlement requirements. Before buying, ask whether replacement receipts are needed, whether payment occurs in stages, and what deadline applies to replacing property. Have the insurer explain the process using a possession you actually own.
Understand the deductible before you need it
A deductible is the part of a covered property loss you bear when it applies. It is different from the premium, which is the price of the policy. The Insurance Information Institute explains the deductible as the amount you pay toward a loss before the insurer’s payment begins.
Suppose an accepted property loss is $3,400 and the applicable deductible is $500. With adequate coverage and no other adjustment, the illustrative insurer payment is $2,900. If the accepted loss is only $350, that same deductible leaves no payment.
You can also compare deductible options using actual quotes. Imagine one option costs $18 monthly with a $250 deductible, while another costs $14 monthly with a $1,000 deductible. The second option saves $48 annually but exposes you to another $750 on an otherwise identical deductible-applicable claim.
At unchanged prices, $750 divided by $48 is about 15.6 years of premium savings. That arithmetic does not predict a claim or tell you which option to buy. It shows the trade-off clearly enough to ask whether the additional deductible would be manageable for you.
What does liability coverage mean for a renter?
Liability coverage addresses covered claims involving injury or damage you cause to others, rather than replacing your own possessions. Depending on the claim and policy, it can also provide a legal defense. Coverage remains subject to the contract’s exclusions and limits.
Think of two different questions. “Can I replace my damaged laptop?” is a property question. “Someone says I caused their loss and wants payment from me” is a liability question. They require different parts of the policy to be examined.
Avoid choosing a liability limit solely because you do not own expensive furniture. The value of your belongings is not a measurement of the damage someone else might allege you caused. Ask the insurer to explain the proposed limit and the situations it would and would not address.
If you have a pet, work from home, regularly host clients or have another circumstance that might affect coverage, describe it plainly. A useful question is: “Does anything about how I live or work change the protection shown in this quote?”
If you cannot stay at home, what happens to the extra bills?
Additional living expenses, often included under loss of use, can help with eligible increases in living costs when a covered loss makes the home uninhabitable. It generally concerns the extra expense compared with normal living costs, not automatic payment of every bill.
Imagine that you normally spend $450 on food during a particular period. While temporarily displaced, you spend $720 because you cannot use your usual kitchen. The difference is $270. That is the additional food expense to discuss with the insurer, not automatically the entire $720.
Now add a temporary room costing $1,050 and additional transport costing $80. If the insurer accepts each expense and the policy permits it, the illustrative total of extra costs is $1,400: $270 plus $1,050 plus $80.
Actual payment depends on the covered event, eligible expenses, savings in normal costs and applicable limits. Before arranging a long stay, ask which accommodation costs are acceptable, how receipts should be submitted, whether advances are available and when benefits end. Record the answer and the name of the person who provided it.
Which gaps deserve a direct question?
Standard renters coverage generally excludes flood and earthquake damage. High-value possessions, sewer backups and business property can also require specific attention or additional coverage. Do not assume all water damage or all property inside the rental receives identical treatment.
Instead of asking only “Is water damage covered?”, describe a situation: water entering from outside, an overflowing drain, or water escaping from an appliance. Ask where the policy addresses each situation. The cause is a more useful starting point than the appearance of a wet floor.
For a valuable item, ask whether there is a separate limit, whether that limit depends on the cause of loss, and what documentation would support extra protection. For work equipment, say who owns it and how it is used. Questions about specific objects tend to produce clearer answers than asking whether “everything” is covered.
Compare quotes using the same shopping sheet
California’s insurance regulator encourages consumers to shop and compare residential insurance products, including renters policies. It provides resources for checking insurers and seeking help with insurance questions.
Use the following worksheet for each quote. Leave an answer blank until it is confirmed; do not treat an unanswered question as evidence that coverage is included.
| Detail to record | What to write down |
|---|---|
| Total policy price | Annual amount and any installment charges |
| Property protection | Overall limit and valuation basis |
| Deductible | Amount and the losses to which it applies |
| Liability | Limit and relevant exclusions |
| Temporary living costs | Available amount, time restrictions and conditions |
| Important possessions | Any separate limits or additional coverage |
| People insured | Names and how household members are treated |
| Assistance | Claim contact and where written answers are available |
When two quotes differ, identify the reason before calling one cheaper. A price comparison is more useful when you can say, “This quote changes the deductible,” or, “This option uses a different valuation basis.”
There is no single premium that can be promised to every reader. Request current quotes for your circumstances and compare the actual offers. An attractive price without understandable coverage terms does not answer what you will receive after a loss.
Prepare a small record that is easy to maintain
Create one folder for your rental and insurance documents. Inside it, keep the policy, a list of belongings and the answers to important coverage questions. Give photos clear names so you can connect them with items in your list.
For example, “bedroom-laptop-model-label” is easier to identify later than a random image filename. For a group of ordinary belongings, a room photo can help you remember what was there. For an expensive item, a separate photograph and available purchase record give you more detail to work from.
Choose a schedule you can realistically maintain. Review the folder when you move, buy an important item or renew coverage. A short update is easier than reconstructing several years of changes. The goal is a usable record, not a perfect catalogue that you never finish.
What should you do if something happens?
Put safety first. Report theft or vandalism to the appropriate authorities and notify the insurer promptly. Document damaged or missing items, keep expense receipts and ask what the claims process requires before disposing of damaged property. The Insurance Information Institute outlines these basic steps for renters claims.
Keep your account factual. Separate what you personally observed from what you suspect happened. If a date or purchase amount is uncertain, label it as an estimate instead of presenting a guess as an exact record.
During each conversation, note the claim number, date, contact name and next step. If you send documents, keep a copy of what you sent. A simple running list can prevent repeated searches through email when someone asks for an item again.
If a settlement seems different from your expectation, ask for a breakdown: accepted value, depreciation, deductible, limits and any excluded amount. This makes the question specific. “Please explain this $300 deduction” is easier to investigate than “The payment seems wrong.”