Why a dental insurance card does not tell you the final price
You visit the dentist expecting a routine appointment. After an examination, the dentist recommends treatment and the receptionist gives you an estimate. You have insurance, but there is still a substantial amount beside “patient responsibility.”
Where did that number come from?
To understand it, you need more than the name of your insurer. You need to know whether the treatment is covered, which price the plan recognizes, whether your deductible applies and how much benefit remains.
This guide explains those questions in everyday language. It focuses on common U.S. dental insurance arrangements, particularly adult coverage. Individual policies and children’s benefits can work differently. All dollar examples are invented for explanation, not current quotes or guaranteed payments.
What is dental insurance?
Dental insurance helps pay for eligible dental services under a contract. You pay a premium to maintain coverage, and the insurer contributes toward covered care according to the plan’s rules.
Coverage may be available through an employer, through an individual purchase or as part of another insurance arrangement. A plan can cover some services more generously than others.
For example, preventive appointments, fillings and crowns may fall into different benefit categories. The category affects how the bill is shared, but classification varies between plans. Never assume that one insurer treats a procedure the same way another does.
A useful first question is: “What does this plan contribute toward the particular care I expect to need?” That produces a more practical answer than asking whether a plan has “good coverage.”
Does regular health insurance include dental care?
Not necessarily. HealthCare.gov explains that some Marketplace health plans include dental benefits, while separate dental plans are also available. Adult dental coverage is not an essential health benefit that every Marketplace health plan must offer.
Children’s dental coverage is treated differently. In the Marketplace, it must be available for children aged 18 and younger, either within a health plan or separately.
Check the actual benefits rather than assuming a medical insurance card also provides routine dental protection. If your employer offers several benefits, identify which document belongs to the dental plan before copying limits or deductibles.
Understand the main plan types
| Arrangement | How it generally works | What to check |
|---|---|---|
| Dental PPO | Uses a provider network and usually offers some out-of-network benefits | Dentist participation and how costs differ outside the network |
| Dental HMO | Typically uses a primary dentist and a defined network | Specialist referrals and the schedule of patient charges |
| Indemnity insurance | Generally offers broader provider choice, with reimbursement under the contract | Whether you pay upfront and how reimbursement is calculated |
| Dental discount plan | Offers participating-provider discounts in return for a membership fee | Discounted prices and participating dentists |
A discount plan is not insurance. You pay the participating dentist’s discounted charge rather than receiving an insurance claim payment. PPOs, HMOs and indemnity arrangements also differ in how care is accessed and paid for.
Do not compare a discount membership price with an insurance premium as though the products provide identical benefits. Ask each provider to explain what happens when you receive the same proposed treatment.
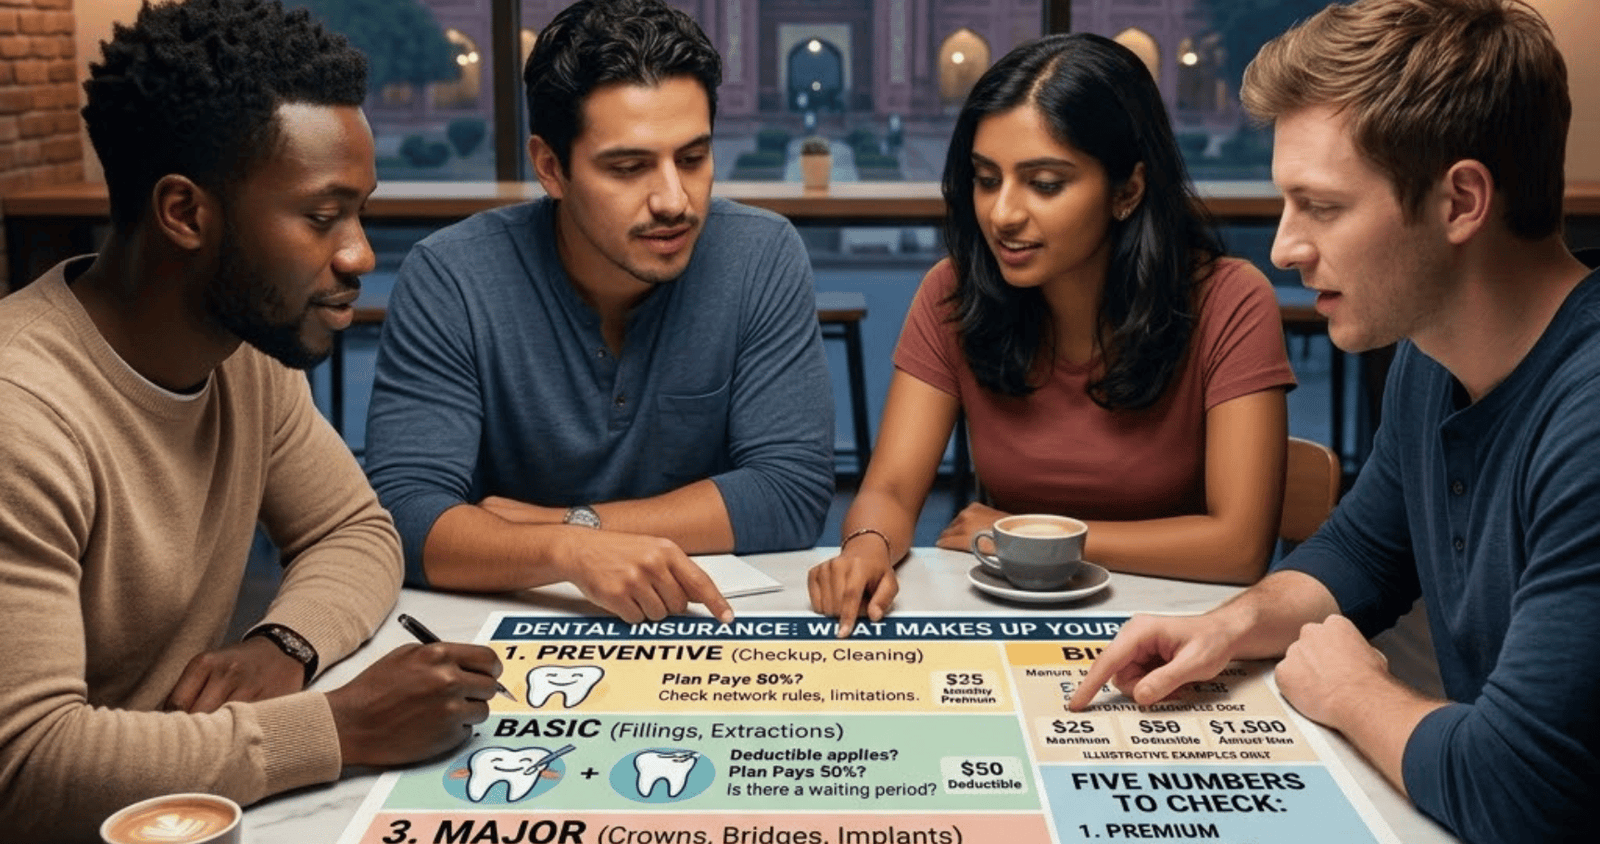
The five numbers that shape your bill
1. Your premium
The premium is the recurring amount you pay for coverage. For an annual comparison, multiply a constant monthly payment by twelve.
A $32 monthly payment becomes $384 for the year. A $48 monthly payment becomes $576. The difference is $192 before either plan pays anything toward treatment.
Use your own payment after any employer contribution already reflected in the quoted price. Otherwise, you might compare the full cost of one plan against only your share of another.
2. Your deductible
The deductible is an amount you may need to pay before certain benefits begin. Some services may be exempt from it.
3. Your copayment or coinsurance
A copayment is a specified amount. Coinsurance is a percentage of an eligible charge. Check whether a listed percentage describes the insurer’s share or your share.
4. The plan’s annual benefit maximum
This generally limits what the dental plan pays during its benefit year. It is not the same thing as a limit on your own spending.
5. Any separate lifetime limit
Some benefits, such as orthodontic coverage, may have a lifetime limit rather than a fresh annual allowance.
Write these numbers on one page. Keeping them together makes a treatment estimate much easier to follow.
An annual maximum usually limits the insurer’s payment
This is an easy detail to misunderstand.
If an adult dental policy has a $1,500 annual benefit maximum, that usually means the insurer will pay no more than the applicable allowance during the benefit period. It does not mean you can never spend more than $1,500 yourself.
Payments already made can reduce the remaining benefit. Some plans exclude certain preventive services from that calculation, so check which claims count. Delta Dental explains that the maximum concerns the insurer’s contribution, rather than the deductible or copayments you pay.
Example: why a headline percentage can overstate the payment
Assume the following:
| Detail | Illustrative amount |
|---|---|
| Allowed treatment charge | $2,000 |
| Insurer’s share after deductible | 50% |
| Deductible remaining | $0 |
| Annual benefit still available | $600 |
Half of $2,000 is $1,000. However, the remaining benefit in this example is only $600.
The modeled insurer payment is therefore $600, leaving $1,400 of the allowed treatment charge for the patient.
This example assumes the procedure is eligible, no other limitation applies and the provider does not charge an additional amount beyond the allowed fee. The calculation shows why “50% covered” is not enough information by itself.
How a deductible changes a treatment estimate
Consider a covered procedure with an allowed charge of $300. Suppose the patient has a $50 deductible remaining and the insurer pays 80% of the eligible amount after that deductible.
The calculation is:
- Subtract the $50 deductible from $300, leaving $250.
- Apply the insurer’s 80% share to $250.
- The insurer’s illustrative payment is $200.
- The patient pays $100: the $50 deductible plus $50 coinsurance.
| Part of the bill | Amount |
|---|---|
| Allowed treatment charge | $300 |
| Patient’s deductible | $50 |
| Patient’s coinsurance | $50 |
| Insurer’s payment | $200 |
| Patient’s total | $100 |
The deductible is included in that $100. Adding another $50 would count it twice.
This is a simplified worked example, assuming sufficient benefits remain and the contract applies the deductible before coinsurance. Ask the insurer to confirm the calculation for your actual procedure.
Why your dentist’s network status matters
A dental PPO generally distinguishes between participating and nonparticipating providers. A dental HMO typically relies more heavily on its specified network and referral arrangements. Choosing a provider outside the relevant arrangement can change or eliminate benefits.
When making an appointment, ask a precise question:
Does this dentist participate in the exact network used by my plan at this office location?
“Do you accept my insurance?” may not resolve the issue you are trying to clarify. Ask both the insurer and the dental office to confirm participation, then request a written estimate for planned treatment.
Record the plan name, office location and date of confirmation. That gives you something concrete to refer to if the information later seems inconsistent.
What commonly falls under dental coverage?
Plans often organize services into categories such as preventive, basic and major care. They may also address orthodontics separately.
| Service to ask about | Detail worth confirming |
|---|---|
| Examination or cleaning | Frequency rules and whether a deductible applies |
| X-rays | Which images are covered and how often |
| Filling | Covered materials and the patient’s share |
| Root canal | Classification under the specific plan |
| Crown | Waiting period, benefit percentage and replacement restrictions |
| Implant | Whether any part of treatment is covered |
| Braces or aligners | Eligibility, age restrictions and separate benefit limits |
These are questions to investigate, not promises that every listed treatment is included. The NAIC notes that coverage varies and that exclusions, waiting periods and service limitations can affect benefits.
Take a proposed treatment plan to the insurer rather than relying only on a category label. The more specific the proposed service, the more useful the answer can be.
Waiting periods can matter when you already need treatment
Some separate dental plans have waiting periods for adult services. You may pay premiums while waiting for the affected benefits to become available. HealthCare.gov advises checking these requirements before enrolling.
If you already have a treatment recommendation, ask:
- When does the policy start?
- When does coverage for this particular procedure start?
- Does prior coverage change the waiting requirement?
- Is there another exclusion that would affect the treatment?
- What happens if treatment has already begun?
Do not assume that buying a policy today makes tomorrow’s procedure eligible. Equally, do not assume every plan has the same waiting rules.
Discuss treatment urgency with your dentist. Insurance timing and clinical timing are separate questions, and a financial comparison cannot determine whether postponement is appropriate.
Check limits beyond the annual maximum
A plan may restrict how frequently it pays for a service. It may also exclude certain treatments or apply a limitation involving a condition that existed before enrollment, such as an already missing tooth. These restrictions vary by contract.
Make your questions concrete. Instead of “Are cleanings covered?”, ask when the next cleaning would qualify under your plan’s timing rule.
Instead of “Are crowns covered?”, ask how the insurer would treat the proposed crown, including any rule about replacing previous dental work.
Write down the answer beside the proposed procedure. A general benefits brochure may be a useful starting point, but it does not settle every detail of an individual estimate.
Request a written estimate before major treatment
Your dental office may be able to submit proposed treatment for a benefit estimate, often called a predetermination. Some arrangements require authorization for particular services or referrals.
The ADA explains that estimated payments are not necessarily guaranteed. Eligibility, remaining benefits or other circumstances can change between the estimate and the actual treatment date.
Ask for an estimate that separates:
- The proposed procedures.
- The provider’s charges.
- The amounts recognized by the plan.
- Expected insurance payments.
- Expected patient payments.
- Any unresolved coverage questions.
An unexplained total is difficult to check. A breakdown lets you ask about one item at a time and understand which assumptions could change.
Compare two plans using an entire year
The monthly premium matters, but it should be considered alongside what you expect to pay for care.
Here is an invented comparison:
| Item | Plan A | Plan B |
|---|---|---|
| Monthly premium | $25 | $45 |
| Annual premiums | $300 | $540 |
| Estimated patient payments for the same planned care | $700 | $350 |
| Illustrative annual total | $1,000 | $890 |
Plan B costs $240 more in premiums but reduces the modeled treatment payments by $350. In this example, its annual total is $110 lower.
Now consider a different scenario in which patient payments are $100 under each plan. Plan A would total $400 and Plan B would total $640. The lower-premium plan would cost less in that scenario.
Neither table predicts your dental needs. They show why a useful comparison needs both a premium figure and a clear description of the care being compared.
Do not use the insurer’s maximum benefit as if you are guaranteed to receive it. Compare the expected payment for eligible services, not simply the largest number in the brochure.
Build a simple comparison worksheet
Use one row for each question and one column for each plan. Leave an answer blank until you can verify it.
| Question | Information to record |
|---|---|
| What will I pay for coverage? | Annual premium and any additional charges |
| Can I use my dentist? | Confirmed network and location |
| Which deductible applies? | Amount and affected services |
| What will the plan pay? | Service-specific percentages or benefit schedule |
| What caps apply? | Annual and separate lifetime limits |
| When can benefits begin? | Effective date and relevant waiting periods |
| What may be excluded? | Restrictions affecting your proposed care |
| What is still unclear? | Questions requiring a written response |
Use the same proposed care when comparing estimates. Otherwise, you might be comparing different treatment rather than different insurance.
For example, if one estimate includes a consultation and imaging but another includes only the procedure, the totals do not answer the same question. Ask the office to identify the missing pieces before deciding that one option costs less.
Read the treatment estimate and final paperwork together
Keep the original estimate, any insurer response and the final bill in one place.
When the amounts differ, identify the changed component. Did the procedure change? Did another claim use some remaining benefit? Was a deductible still outstanding? Did the insurer recognize a different amount?
The ADA notes that other benefit payments or changes in eligibility can affect what is ultimately payable, even after a preliminary estimate.
Ask for a plain-language explanation before assuming a difference is necessarily a mistake. If something does appear incorrect, describe the exact item and amount you are questioning.
A short message such as “The estimate showed $400 payable by the plan, but the final statement shows $250; please explain the $150 difference” gives the recipient a specific issue to investigate.